
401(k) Mistake: How Early Retirees Pay Too Much Tax [Video]
by Financial Design Studio, Inc. / November 5, 2026
If you are an early retiree, the last thing you want is to make a 401(k) mistake and get hit by taxes and penalties. In this video, Michelle shares which ages that taxes or penalties can affect for both a 401(k) and an IRA.
During your career, your 401(k) strategy was straightforward: max out your contribution, take the company match, and don’t touch it. But now with a retirement date around the corner and $875,000 or more in tax-deferred accounts, that default can lead to costly mistakes.
Hi, my name is Michelle, and I’m a financial advisor here at Financial Design Studio. Every day I help business professionals like you retire in a tax efficient way. So in today’s video I want to talk about how to access your 401(k) penalty free as you prepare to retire early.
What is the Impact of Taxes on a 401(k)?
Here’s a situation we hear from many clients as they start to work with us. They have good jobs, they’ve saved really well, and they have over $875,000 in their 401(k). It seems like they’ve been set up for a strong retirement. But without careful planning and implementation, we as advisors know that taxes and penalties can quickly ruin that.
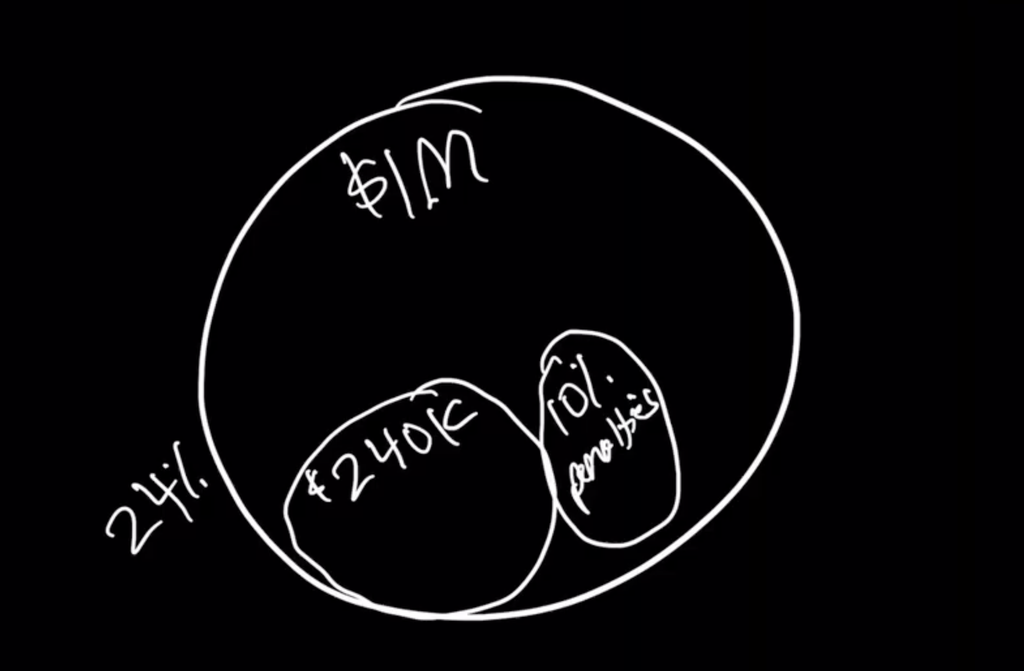
So let me show you how. Let’s assume that you have $1M dollars in your 401(k) account. Now many people look at that and say, “I have a million dollars to spend in retirement!” However, what they forget is that you have to pay income tax on these funds when they come out of your account.
So let’s just assume that you’re always in the 24% bracket. This is kind of a middle bracket for higher income earners, corporate executives. And so let’s assume we’re gonna pay 24% of this account in taxes. That’s $240,000 of this account that is gonna go to pay income taxes. It can feel a little deflating.
However, what could actually make it worse is if you also have to pay another 10% in penalties because of timing. What we really want to avoid is paying any more penalties or income tax than we need to.
Don’t Rush to Rollover Your 401(k)
There comes a point when traditional “save and then you can spend” doesn’t cut it as retirement advice, especially as we see people retiring earlier and earlier.
The reason why I wanted to spell this out is because traditional advice would tell you to rollover that 401k into an IRA as soon as you leave your company. However, if you do that, and you want to retire early, you will have to pay penalties for withdrawing from your IRA at the wrong age.
That’s what we want to talk about today. How can you withdraw from your 401(k) so that you avoid penalties and pay tax at the lowest rate?
What Ages Have Penalties?
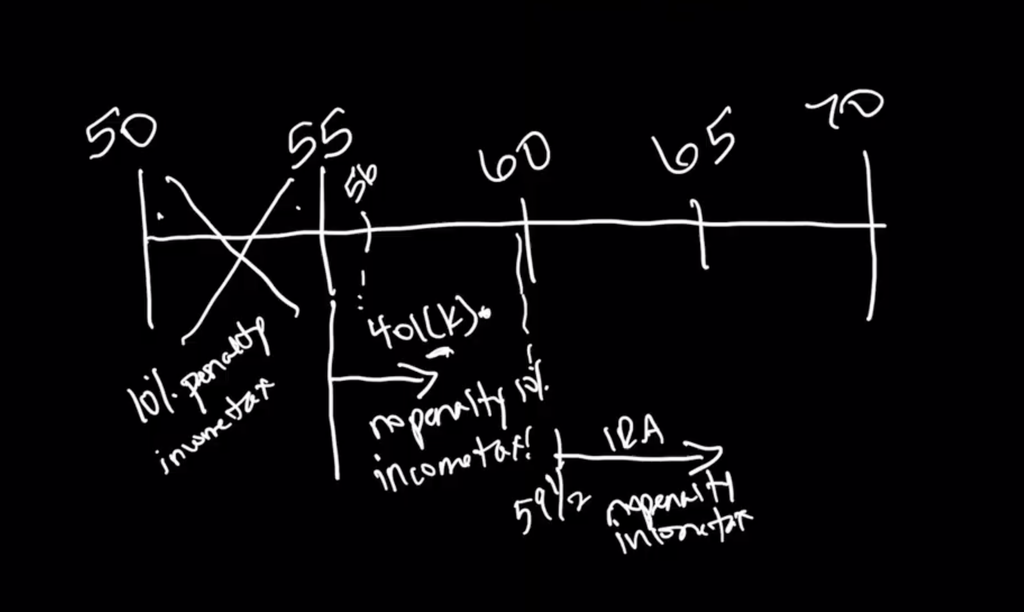
Now, let’s talk about the age that you distribute funds from your retirement account. Now, if we think about how these accounts were designed for the government, they are meant to be for retirement. So I’ve drawn this timeline where we can see different retirement ages, taxes, and penalties.
Before age 55, there is a 10% penalty for withdrawing funds out of either your 401(k) or your IRA. You will also have to pay income tax on any funds that you take out. That’s a double hit to your $1M retirement account.
Once you reach age 55, you can take funds out of your 401(k) account without penalty. It’s called the rule of 55. You won’t face this penalty of 10%, but you will have to pay income tax on those funds. Now if you want to avoid that 10% penalty, you need to make sure you withdrawing it from there.
Now, once you reach age 59 1/2, you can take money out of your IRA, without penalty. Of course you will have to pay income tax on those funds also.
Two Types of Early Retirees
Now, as we think about, there are usually two different types of people we see retiree. There is the first person who has saved all their money into their 401(k). These are their biggest accounts. So when they retire, they need to take money out of this account the day they retire. And then you have a client who has saved money into 401(k), but they also have taxable accounts, Roth IRAs, deferred compensation, or employer stock.
Let’s you’re someone who wants to retire early, say at age 56. You need to take money out right away from your 401(k). Well you can see on the timeline that at age 56, the only account without penalty at that age is the 401(k). But if you have saved well and have other types of accounts, you could roll over that 401(k) into an IRA because you know that you don’t need those funds yet.
What’s really important here is that it’s not all or nothing. You can split your 401(k), leaving some money in there and then take the rest and put it into an IRA. So it doesn’t have to be all or nothing.
This is why retirement planning is so important. You need to know how much you need, what age you need it, and more importantly, assurance that the money will be there when you need it. You shouldn’t make moves to retire or roll over accounts without knowing these details.
Next Steps
At the end of the day, it’s questions like these that are why people nearing retirement work with financial advisors like us who manage investments alongside comprehensive planning. This is how you can create a tax efficient retirement.
if you resonated with any of these topics, you can find our free retirement planning guide linked below.
And if you want our team of financial advisors to support your retirement plan, this is what we do best. Our team specializes in tax efficient retirement planning for individuals with executive compensation. So you stay on track all year, every year, reach out to our team at to schedule a 45 minute consultation.
We will see you there or in the next video!
Bonus: Our Free Retirement Planning Guide!
Ready to take the next step?
Schedule a quick call with our financial advisors.


Recommended Reading
Save on Taxes in Your 401(k) with Net Unrealized Appreciation [Video]
In this video, we explain what Net Unrealized Appreciation is, how to rollover your 401(k), and how it can impact your retirement taxes.
How do I Diversify My RSUs Before Retirement? [Video]
In this video, we explain how ESPPs, Blackout periods, and the Wash Sale rule all shape what you should do with RSUs before retirement.
Financial Design Studio, Inc.
We are financial advisors in Deer Park and Barrington, IL. A team with a passion for helping others design a path to financial success — whatever success means for you. Each of our unique insights fit together to create broad expertise, complete roadmaps, and creative solutions. We have seen the power of having a financial plan, and adjusting that plan to life. The result? Freedom from worrying about the future so you can enjoy today.